Licensed Nevada Realtor, HomeSmart Encore, license S.0179652. 5.0 from 32 Google reviews.
What happened to mortgage rates in September, and what does it mean for your Las Vegas home? Answer: The 30-year fixed jumped to 6.95 percent in Freddie Mac’s September 17 survey, its highest reading of 2026, the day after the Federal Reserve raised its benchmark rate by a quarter point. Buyers now pay more per month for the same house, so price and presentation carry more weight for you as a seller than they did in August.
August gave you, the seller, a breather. September took it back. Rates climbed four weeks in a row, and then the Federal Reserve did something it had not done all year: it raised rates instead of holding them.
If you are selling this fall, you need the real numbers, not the headlines. Here is where rates stand, what the Fed actually said, what the Las Vegas real estate market looks like right now, and the moves that protect your price.
Where Rates Stand Right Now
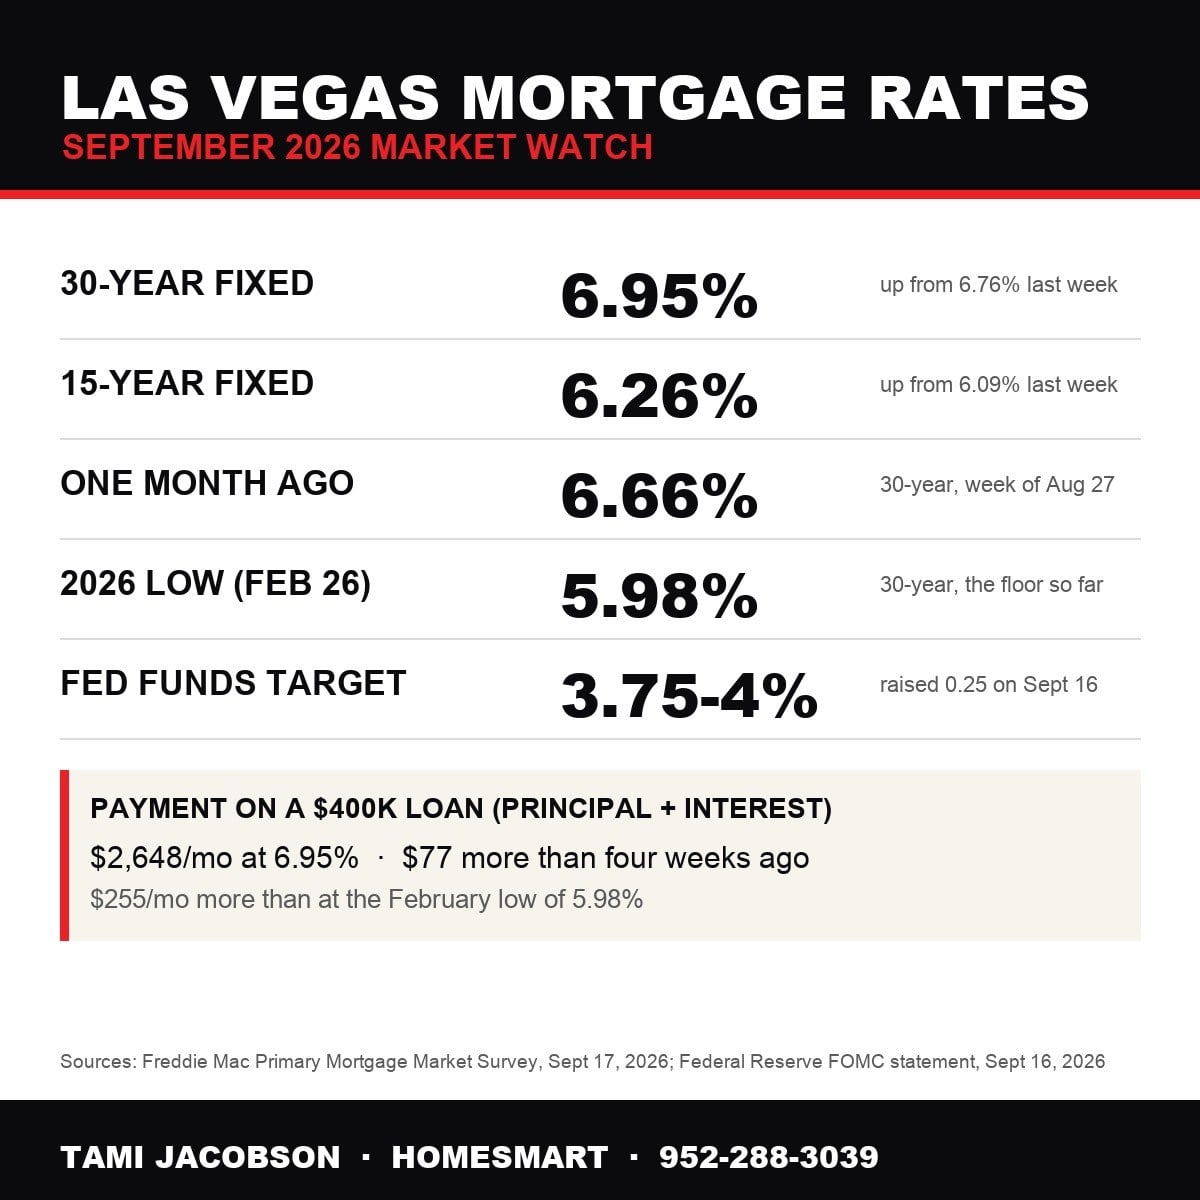
Your numbers come straight from Freddie Mac’s Primary Mortgage Market Survey for the week of September 17, 2026:
- 30-year fixed: 6.95 percent, up from 6.76 percent the week before
- 15-year fixed: 6.26 percent, up from 6.09 percent the week before
- Four weeks earlier, on August 27, the 30-year sat at 6.66 percent
- The 2026 low came on February 26, at 5.98 percent
I checked every weekly reading Freddie Mac has published this year, and two facts stand out for you. First, 6.95 percent is the highest 30-year reading of 2026. Second, the one-week jump from 6.76 percent was the biggest weekly increase of the year. A year ago the 30-year averaged 6.26 percent, so your buyers face noticeably higher financing costs than last fall.
What the Fed Did on September 16
On September 16 the Federal Reserve raised its target for the federal funds rate by a quarter point, to a range of 3.75 to 4 percent. The vote was 12 to 0. If you followed the summer headlines, you saw the Fed hold that rate at 3.50 to 3.75 percent through its June and July meetings, so this marks a clear change of direction for your buyers.
The reason, in the Fed’s own words from its September 16 statement: “Inflation remains elevated.” The same statement describes the economy as expanding at a solid pace, with job gains keeping up with the workforce. For you, that means the Fed chose to fight inflation over easing borrowing costs.
Keep one detail in mind before you react. The Fed does not set mortgage rates. Freddie Mac’s survey averages loan rates offered from the prior Thursday through Wednesday, so the 6.95 percent reading mostly reflects the week leading into the Fed’s decision. Mortgage pricing moved ahead of the announcement, the way it usually does. Nobody knows where rates go from here, and you should be wary of anyone who claims to.
What the Las Vegas Market Looks Like
Rates are only half the story. The other half lives in the local numbers. The most recent month Las Vegas REALTORS has posted on its housing market statistics page is July 2026. Here is what it shows for your market.
| Measure | Single-family homes | Condos and townhomes |
|---|---|---|
| Median sold price | $480,000 | $290,000 |
| Homes sold | 2,046 | 541 |
| Median asking price, active listings | $528,000 | $275,000 |
| Active listings | 9,811 | 3,329 |
| Active listings with no offer | 7,442 | 2,719 |
Two ratios matter most for you, and they come from simple math on those figures. Divide 9,811 active single-family listings by 2,046 sales and you get about 4.8 months of supply. Divide 7,442 listings without an offer by 9,811 active listings and you get roughly 76 percent sitting without an offer.
Notice the gap between the median asking price of $528,000 and the median sold price of $480,000. Those measure different groups of homes, so the gap is not a discount. It does tell you something useful: buyers close on homes priced near the middle of the market, while many higher-priced listings wait. Your price decides which group you join.
What This Means If You Are Selling
Start with the payment math, because your buyer does. On a $400,000 loan, principal and interest at 6.95 percent comes to about $2,648 a month. At the August 27 rate of 6.66 percent, the same loan cost about $2,571. That gap of $77 a month sounds small, yet it adds up to real money every year, and it pushes some buyers out of their price bracket entirely.
Here is the version that hits your price. A buyer who budgeted around $2,571 a month in late August now qualifies for a loan closer to $388,000 at today’s rate, instead of $400,000. Multiply that across every buyer in your price band, and you see why a sharp pricing strategy matters more this month than last.
What works for you right now:
- Price to the sold numbers, not to your neighbor’s asking price. The table above shows why.
- Fix what an inspector will flag before you list. Buyers stretching on payment have less room for surprise repairs.
- Invest in presentation. Clean, bright, well-photographed homes win the showings that do happen.
- Consider a seller concession toward the buyer’s rate as an alternative to a bigger price cut. Your lender and theirs will explain the options, and I will run the numbers with you.
If you want your own number before you decide anything, start with a free home value report. No cost, no obligation.
What This Means If You Are Buying
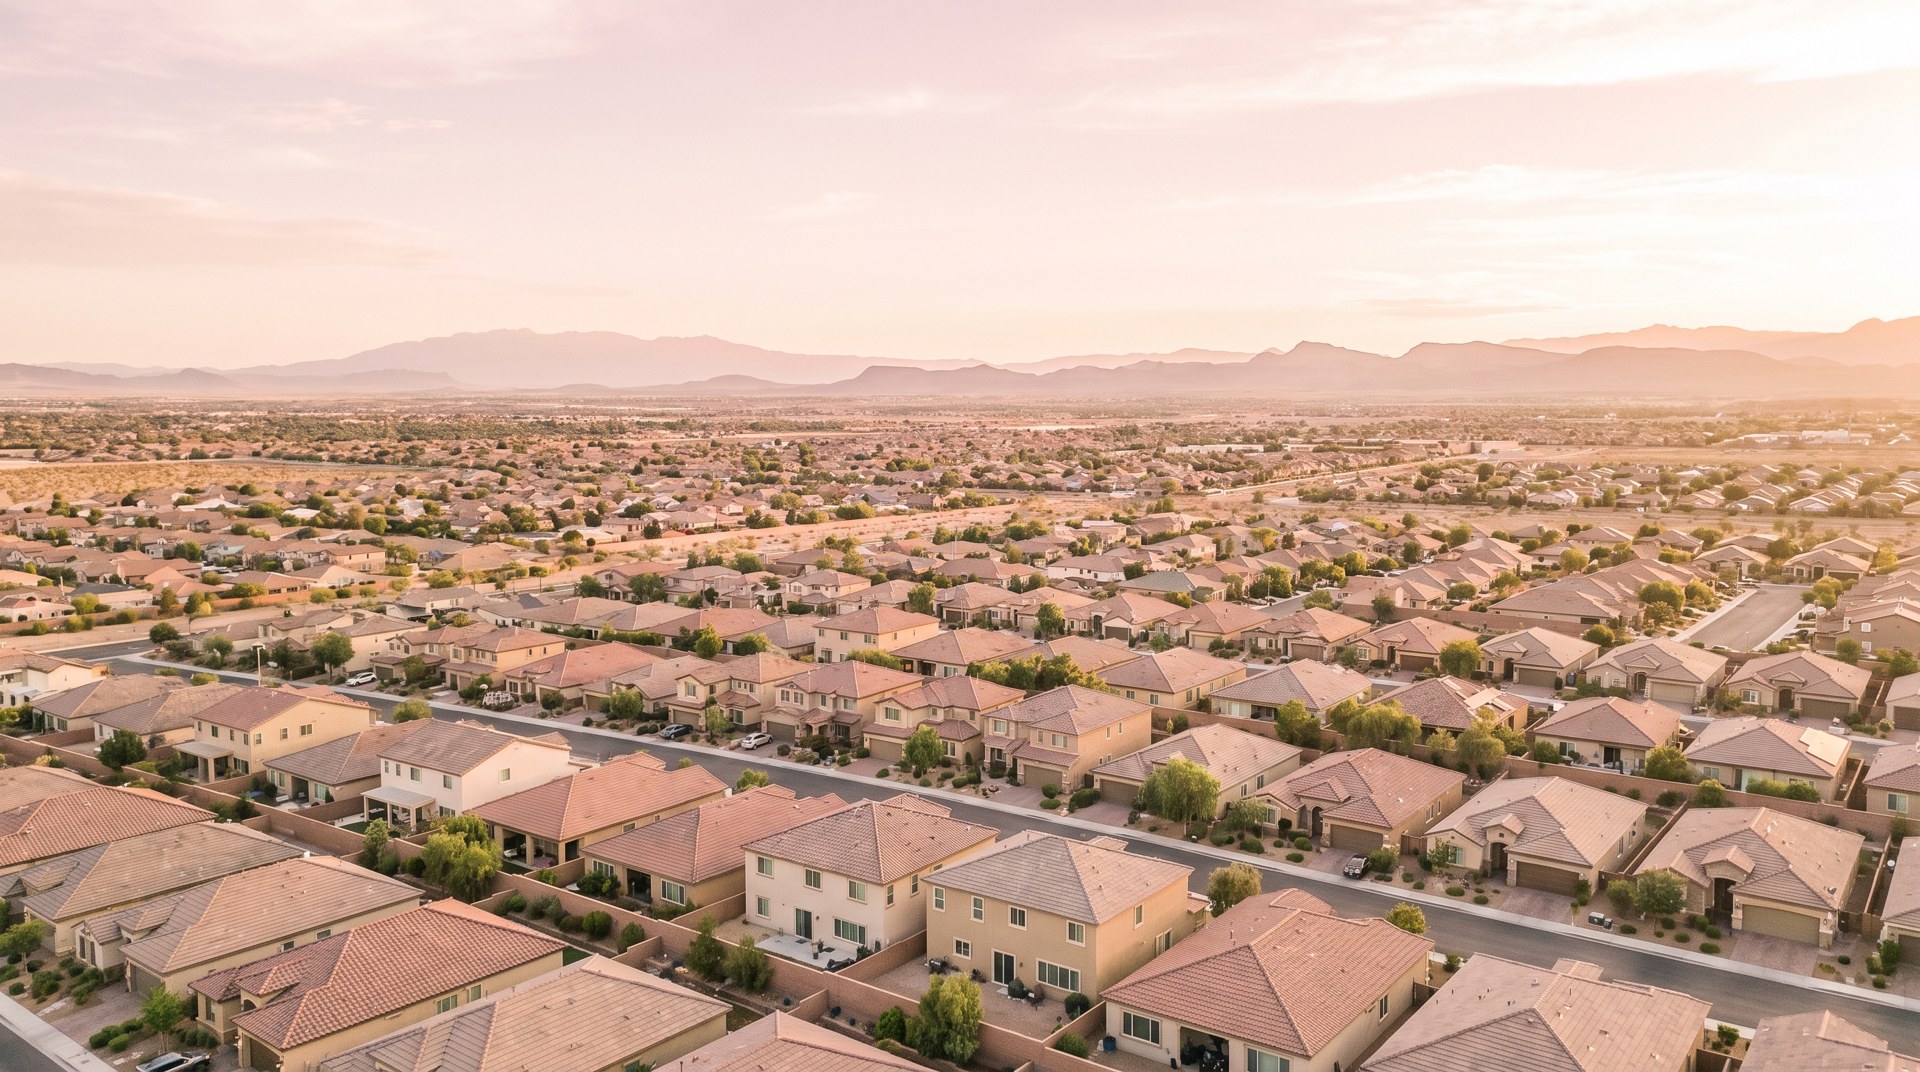
Higher rates cost you, and I will not pretend otherwise. They also bring something buyers lacked a few years ago: choice and time. With 7,442 single-family listings sitting without an offer in July, you have room to compare, inspect properly, and negotiate on terms instead of racing to beat five other offers.
Get pre-approved before you shop so you know your real payment at today’s rate, not last month’s. The Consumer Financial Protection Bureau’s home buying guide walks you through loan estimates and how to compare lenders. I am not a lender and none of this is lending advice, so take your specific questions about rates and qualifying to a licensed loan officer.
If you are weighing whether to wait for lower rates, read my take on whether to sell now or wait. The same timing logic applies from the buyer’s side of the table.
Your Move This Fall
Rates moved against buyers this month. Your home did not lose its value because of a headline, but the margin for a wrong list price just got thinner. The sellers who win this fall price from real sold data, fix the obvious issues up front, and launch with photos that stop the scroll.
That is exactly how I work with every seller. Every one of my 32 Google reviews is five stars, and it starts with telling you the truth about your number, even when the market shifts under us. Last month’s August market update shows how fast this picture changes, and my guide on how long it takes to sell in Las Vegas explains how pricing drives your timeline.
Las Vegas Mortgage Rate Questions, Answered
What are mortgage rates in Las Vegas right now?
Freddie Mac’s national survey for September 17, 2026 puts the 30-year fixed at 6.95 percent and the 15-year fixed at 6.26 percent. Your own rate depends on your credit, down payment, and loan type, so ask a licensed lender for a quote on your exact situation.
Did the Fed raise interest rates in September 2026?
Yes. On September 16, 2026 the Federal Reserve raised its federal funds target by a quarter point, to 3.75 to 4 percent, citing elevated inflation. It had held the rate steady at its June and July meetings, so your buyers felt a change in direction.
Does a Fed rate hike raise mortgage rates?
Not directly. The Fed sets a short-term rate, while mortgage rates follow the bond market and lender pricing. In September the two moved in the same direction, and your buyers saw mortgage rates climb in the weeks before the Fed announced its decision.
Is it still a good time to sell a house in Las Vegas?
It depends on your price, your timeline, and your next move. July data from Las Vegas REALTORS shows about 4.8 months of single-family supply and most listings still waiting for an offer, which rewards sellers who price to recent sales. A free home value report gives you your number before you decide.
How much does a higher rate change my buyer’s payment?
For your buyer, on a $400,000 loan, moving from 6.66 percent to 6.95 percent raises principal and interest by about $77 a month. Compared with the 2026 low of 5.98 percent, today’s payment runs about $255 a month higher.
Where do Las Vegas home prices stand right now?
The most recent month Las Vegas REALTORS has published is July 2026, with a median single-family sold price of $480,000 and a median condo and townhome sold price of $290,000. I update these numbers for you as new months post.
Want to know what these rates mean for your home?
Call me and I answer. Same day, every time.
Like this article? Add Tami Jacobson as a preferred source, and you are more likely to see our articles in Google’s Top Stories.